Deal Notes
Transactions worth understanding. Swipe through each one for the facts, what it means, and where it fits.
The deal
Onyx Insight – Macquarie Capital
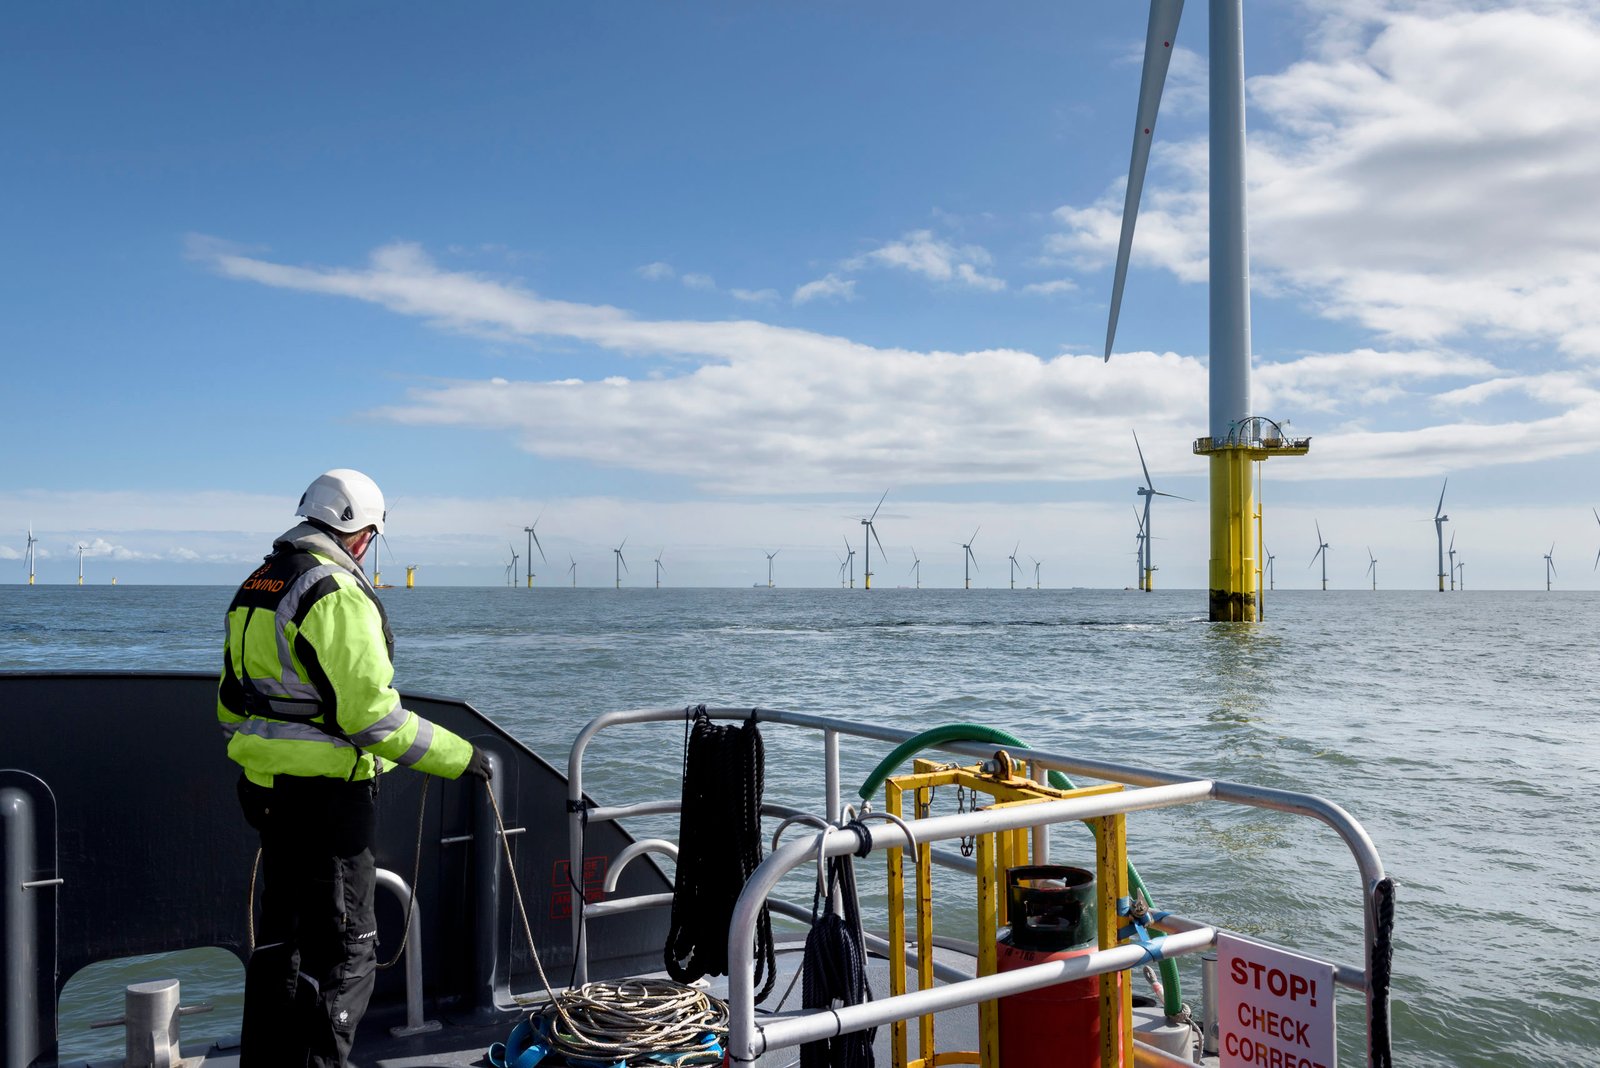
Macquarie bets on predictive maintenance, before the wind industry knew it needed one.
32,000+
Turbines Monitored
45+
Countries
Who's involved
Onyx Insight
Technology Provider
A UK-based predictive maintenance company, using sensor data and AI to flag wind turbine component failures before they happen.
Macquarie Capital
Buyer
The investment banking and asset management arm of Macquarie Group, backing growth-stage companies across infrastructure and technology.
Key terms
- 11 March 2024: Macquarie Capital acquires ONYX Insight. Deal value undisclosed.
- 15 July 2026: ONYX partners with Aviva's Global Risk Management Solutions, aiming to reduce operational and insurance risk for wind asset owners, with failure detection able to flag risk up to two years in advance.
- September 2026 ONYX launches Cortex, its integrated reliability platform, at WindEnergy Hamburg, trained on 50,000 documented wind failures and claiming up to 70% less unplanned downtime and up to 95% fewer false alarms.
The Bigger Picture
Reliability isn't just an operational issue for offshore wind. It's a financing issue.
The large pools of capital this industry depends on rely heavily on debt, and what institutional lenders want is a steady track record of operational projects to justify treating wind as low-risk. Downtime undermines exactly that as every outage is a dent in the performance record lenders are pricing against. That downtime is usually managed through O&M service agreements, but GWEC estimates demand for wind technicians will rise from around 475,000 today to 628,000 by 2030, a roughly 50% jump in five years. As that pool stretches thinner, downtime risks growing with it, denting both individual project returns and the sector's broader risk profile.
The result is a reinforcing cycle, where more downtime raises the perceived risk of wind as an asset class, which raises the cost of capital.
Our take
This has created an opening, which ONYX is now capitalising on with its recent partnerships and technology launches.
The solutions the wind industry needs, are not so much about reinventing the wheel, rather strengthening it. ONYX does this through real-time analytics, giving developers the chance to optimise existing operations, by bringing in expertise and parts before a failure happens, rather than scrambling to react once it has.
The outcome is a smarter use of a scarce resource. Instead of service agreements triggering only after a fault has already cost downtime, operators get enough notice to schedule repairs around the crews and vessels they've already booked, easing pressure on that stretched talent pool while giving lenders the clearer, earlier read on failure risk they need to keep financing the asset class.
Press
Macquire
Macquarie Capital acquires renewable energy data analytics provider ONYX Insight
Renewable Energy Magazine
Aviva and Onyx Insight partner to manage wind turbine insurance risks and help extend asset life
Onyx Cortex Page
Tailored intelligence that connects condition, performance, and operating decisions across your growing, complex fleet.
The deal
Africa GreenCo closes $21.5M fundrasing round
Development funds are quietly derisking Africa's renewable energy rollout.
900MW
PPA Capacity
$21.5M
Deal value
Who's involved
Africa GreenCo
Sponsor
An energy trader with operating licenses in Zambia, Zimbabwe, Namibia and South Africa. It has traded more than 1.4 TWh of electricity so far in 2026. Beyond trading, the company acts as a bankable offtaker, through renewable energy independent power producers (IPPs)
PIDG & Impact Fund Denmark
Co-investor
PIDG: Development finance group backing infrastructure across Africa.
Impact Fund Denmark: Denmark's state development finance institution, investing in green energy and infrastructure across emerging markets.
Key terms
- $11.5 million raised by Africa GreenCo from existing shareholders the Private Infrastructure Development Group (PIDG) and the Impact Fund Denmark (IFDK).
- US$21.5 million now raied in total, following a recent commitment from Sanlam Alternative Investments.
- This deal follows IFDK previously helping mobilise a €50 million guarantee facility in 2025, that has enabled Africa GreenCo to attract further private capital.
- 900MW: the funds specifically enable Africa GreenCo to back up to this much in renewable power purchase agreements across the continent
Our take
For a continent like Africa, where government de-risking mechanisms, like the UK's Contracts for Difference, are largely absent, it falls to private structures like Africa GreenCo to take on that role instead. That's what makes development funds backing this deal worth following: it signals that in countries with weaker institutional capacity, it will be energy traders and corporates, not government schemes, leading the way on deployment.
Following investment trends in the Global South offers a genuine, early look at what market structures for electrification will actually need to look like in these emerging economies. These are dynamic regions that will need to find non-state solutions to rapid electrification, answers wealthy economies may increasingly need to pay attention to too, as confidence in their own long-term political and policy certainty comes under greater strain.
The bigger picture
Demand for electricity in Africa will keep growing, but meeting it with clean energy requires de-risking events, usually offtakes, to unlock the debt financing developers need to build and operate new project.
In Africa, the existing model forces developers to sign contracts with state-run utilities that have weaker payment histories and less secure finances. This adds real risk for banks, whose lending decisions depend on those payments actually arriving.
Africa GreenCo solves this by signing the offtakes itself, then leveraging its coverage across multiple markets to sell onward to whichever utilities can actually pay, essentially acting as a renewable reseller. The outcome for a developer is a diversified, guarantee-backed contract that a bank will actually finance against. This could be the key to rapid deployment of renewables across Africa.
The deal
Fervo Energy — Google geothermal PPA
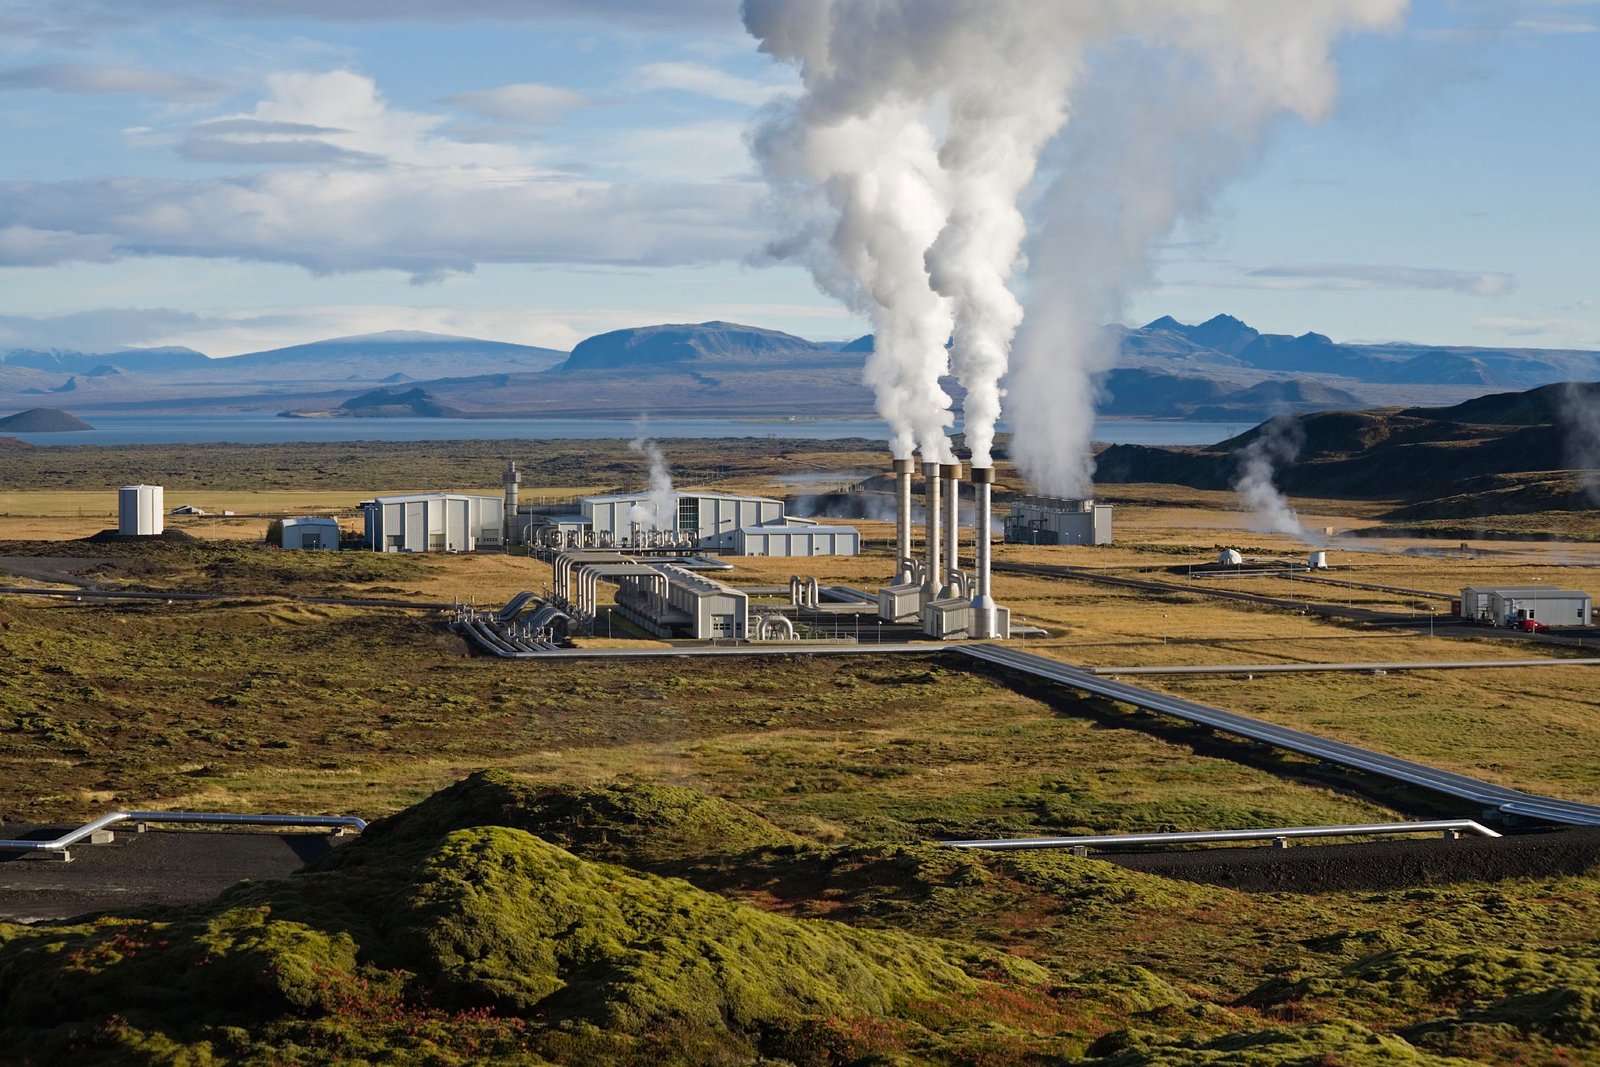
Drilling techniques borrowed from oil and gas, aimed at data centers instead.
396MW
PPA size
$2B+
Fervo's investment
Who's involved
Fervo Energy
Developer & seller
Houston-based next-generation geothermal startup, developing the Cape Station project in southwest Utah. Went public in May 2026.
Buyer
Buying the power for a planned data center in Utah, the exact site not yet finalized. Fervo's longest-standing corporate partner, dating back to 2021.
Key terms
- Cape Station is being built in phases: a 100MW first phase, with an initial 33MW unit expected to start test power in Q4 2026. This 396MW deal covers phase two, targeted for around 2028.
- Google can expand the agreement by roughly 600MW more by June 2030, and separately holds right of first refusal on up to 3GW from Fervo's future plants. That's Google locking in long-term access to Fervo's whole pipeline, not just this one project.
- PPA pricing wasn't disclosed. Fervo has separately stated its own build cost at roughly $7,000/kW for phase one and $5,500/kW for phase two. Despite this being far from cost-competetive with solar and wind, Google is prepared to pay a premium for clean 24/7 reliable energy.
The bigger picture
Geothermal still generates under 0.4% of US electricity today. This deal doesn't change that overnight, but it's a serious vote of confidence from one of the world's largest power buyers. By signing a corporate power purchase agreement, Fervo can overcome the financing barriers that often prevents progress from early-stage development to final investment decisions (FID).
It also fits the same pattern running through Masdar and KKR's deals this year: hyperscalers increasingly financing power generation directly rather than just buying electricity off the grid. AI is the real force behind that shift, data centers need enormous, reliable power, and it's increasingly more effective for hyperscalers to fund the energy innovation itself than wait for someone else to build it.
Our take
The real story here might be workforce, not megawatts. Fervo's biggest working plant to date is a 3.5MW pilot, and this deal jumps straight to 396MW, over 100 times bigger, because Fervo isn't inventing new drilling technology from scratch. It's redeploying a century of oil and gas drilling expertise into a new use case.
That's what makes this a genuinely practical version of a Just Transition, not the phrase, the actual mechanism. Skilled drilling crews have somewhere real to go, and not because it's the right thing to do. It's because it's actually cheaper and faster for Fervo to hire people who already know how to drill than to build that expertise from scratch. A just transition that depends on good intentions rarely survives contact with a budget. One built on genuine cost advantage might.
The deal
Brookfield & La Caisse — Boralex buyout
From public markets to private hands, on a bet that patience is worth paying for.
3,783MW
Capacity
$6.5B
Deal value
Who's involved
Brookfield
Sponsor
One of the world's largest alternative asset managers, with over $1 trillion under management across infrastructure, real estate, credit and private equity. Taking a 70% stake via its flagship infrastructure strategy.
La Caisse
Co-investor
Canada's second-largest pension fund manager, investing for Quebec's public pension plans, with roughly CA$473 billion in net assets. Already Boralex's largest shareholder, now increasing its stake to 30%.
Key terms
- $37.25 per share, all cash. No stock swap involved, so shareholders get certainty now rather than betting on Brookfield's future share price.
- 31.8% premium to the pre-announcement price. That's the gap between what the market was valuing Boralex at and what Brookfield was willing to pay, a sign the board saw more upside ahead than public investors currently did.
Our take
This wasn't a bet on a story. Boralex came into the deal with 3,783 MW of installed capacity, an 8.2 GW pipeline, and $552 million of 2025 EBITDA, a real, cash-generating business. What it lacked was patience from public shareholders, who want returns on a quarterly clock that doesn't match how long infrastructure actually takes to build.
That mismatch is exactly why Brookfield is paying a premium to take it private. Public markets are currently pricing patience very differently than private capital is, and that gap is what's pulling assets like Boralex off the stock exchange.
The bigger picture
Boralex isn't the only one. Large infrastructure funds have been buying out publicly listed renewable platforms at a premium all year, making the same bet: given room to breathe, without needing to justify progress every quarter, these pipelines are worth more.
Demand for power is only growing, from electrification, from AI, from the broader push for energy security. The businesses building that supply aren't getting worse. They're just stuck in a market that wants proof of returns faster than infrastructure can realistically deliver them, and private capital is the one willing to wait it out.
The deal
EAAIF — Ukko Renewable
Patient capital for the projects commercial lenders won't touch yet.
2GW+
Pipeline
$50M
Facility
Who's involved
EAAIF
Lender
The Emerging Africa & Asia Infrastructure Fund, a development-finance-backed fund managed by Ninety One, providing senior secured debt.
Ukko Renewable
Borrower
The Southeast Asian renewable platform of Groupe Duval, developing wind, solar, and hydropower projects across Vietnam and the Philippines.
Key terms
- Funds an initial 2GW+ pipeline within a broader 3GW+ portfolio across Vietnam and the Philippines.
- In Vietnam, projects are prioritised under the country's revised Power Development Plan (PDP8).
- The money exists specifically to get projects to "ready-to-build" status, the stage that's hardest to finance in emerging markets.
Our take
This is a genuinely different kind of capital than most of what we cover. EAAIF exists specifically to fund the early, unproven stage of a project, before it has permits, grid connection, or contracted revenue, the exact point where commercial banks usually won't lend.
Once Ukko gets these projects to "ready-to-build," they become financeable by ordinary commercial lenders. EAAIF's real job here is closing that gap, not chasing the eventual return itself.
The bigger picture
Vietnam and the Philippines both have real policy tailwinds right now, Vietnam's PDP8 framework and the Philippines' Green Energy Auction Programme, but policy alone doesn't build projects. Someone still has to fund the risky early stage.
This is one small deal within a much larger, deliberate strategy: PIDG's 2023-30 plan to mobilise private investment across South and Southeast Asia's energy transition, one greenfield gap at a time.
The deal
EU approves €63B French offshore wind aid
Not a transaction between two companies, a government betting big on de-risking an entire industry.
11.1GW
Total capacity
€63B
Aid approved
Who's involved
European Commission
Approving authority
Cleared the scheme under the Clean Industrial Deal State Aid Framework, concluding it was necessary and proportionate.
French government
Scheme provider
Will allocate the aid through competitive, non-discriminatory tenders for 11 offshore wind farms across the North Sea, Atlantic, and Mediterranean.
Key terms
- Support is delivered as a two-way Contract for Difference, a floating price floor and ceiling, not a fixed subsidy cheque.
- The scheme runs for 25 years, giving developers long-term price certainty across the life of each project.
- Once built, the farms are expected to generate 47.8 TWh annually, roughly 10.6% of France's total electricity consumption.
Our take
The two-way CfD structure is the real story here. Developers get protected from crashing power prices, but the state claws back the upside when prices run high.
That's a very different risk trade than a flat subsidy, and it's specifically designed to make offshore wind bankable without permanently overpaying developers.
The bigger picture
This is one of the largest state aid packages for renewables the EU has ever cleared, and it's explicitly framed around industrial policy, not just climate goals: turbine manufacturing, ports, and grid infrastructure are meant to benefit too.
Europe isn't just buying clean electricity here. It's trying to build the domestic industry that supplies it.

The deal
Masdar — the world's first gigascale 24/7 clean power plant
Solar that keeps the lights on after dark, at genuinely massive scale.
5.2GW
Solar PV
$6.1B
Total project
Who's involved
Masdar
Developer & equity
Abu Dhabi's state-backed clean energy company, contributing $1 billion in equity. Already at 65GW of global clean energy capacity, targeting 100GW by 2030.
13-bank lender consortium
Debt providers
Including HSBC, BNP Paribas, Standard Chartered, and Bank of China, providing the $5.1B debt package alongside regional banks.
Key terms
- Pairs 5.2GW of solar PV with a 19GWh battery storage system, big enough to genuinely deliver power around the clock.
- Developed with Emirates Water and Electricity Company (EWEC), the UAE's federal offtaker.
- Construction broke ground October 2025; operations are expected to begin in 2027.
Our take
Solar's biggest weakness has always been the same: it stops generating the moment the sun goes down. Most projects sidestep that problem rather than solve it, pairing modest storage that covers a few hours at most.
19GWh is a different scale of answer entirely. This project is a genuine attempt to make solar behave like baseload power, not just a daytime supplement to it.
The bigger picture
This sits inside a much larger UAE push: Masdar alone is targeting 100GW of global clean energy capacity by 2030, with active projects spanning Angola, Uzbekistan, and beyond. Gulf sovereign wealth is being deployed into clean energy at a genuinely global scale, not just domestically.
A 13-bank international lending consortium backing a single UAE project also signals how mainstream Gulf renewable infrastructure has become as an asset class for global capital.

The deal
KKR — EDF power solutions North America
KKR's largest renewables bet yet, built on the AI power demand story.
5.6GW
Portfolio
$4.2B
Deal value
Who's involved
KKR
Buyer
Global alternative asset manager, funding the acquisition through its global infrastructure strategy. This is KKR's largest individual investment in renewables to date.
EDF power solutions
Seller
The North American renewables arm of EDF Group, France's state-backed utility giant, divesting after a competitive sale process.
Key terms
- $4.2B equity value, plus up to $390M in potential additional performance-based payments.
- Portfolio includes 26GW of wind, solar, and storage developed to date, plus 17GW under active service contracts.
- EDF power solutions ranks among the top ten owners of renewable capacity in the US, with a nearly 40-year track record.
Our take
This is a portfolio-scale acquisition, not a single project. KKR is buying an integrated platform spanning development, construction, and long-term operations, a bet on operational capability, not just megawatts.
It also signals EDF is choosing to consolidate its focus rather than spread capital across geographies it no longer wants to manage directly.
The bigger picture
KKR was explicit about why: power demand is rising fast in the US, driven by AI data centers, manufacturing reshoring, and broader electrification.
This sits alongside a wider wave of asset recycling among renewable sponsors, increasingly driven by private infrastructure capital competing for platforms tied to data-center-linked demand growth.
The deal
Stegra — green hydrogen steel
While rivals cancel their hydrogen steel plans, Stegra just got paid to keep building.
690MW
Electrolyser
€6.5B
Total package
Who's involved
Wallenberg Investments
Lead equity
Swedish industrial investment group, providing the foundational equity needed to unlock a much larger pool of debt financing behind it.
Mercedes-Benz
Anchor offtaker
One of several automakers, alongside Scania, Volvo, and Porsche, that signed long-term offtake agreements before the financing closed, absorbing the green steel price premium.
Key terms
- 690MW electrolyser, the largest in Europe, powering direct-reduction steelmaking instead of coal.
- €6.5B total package, combining the €1.4B equity round with a much larger debt facility behind it.
- Offtakes signed before financing closed, not after, the sequencing that made the debt bankable at all.
Our take
This financing closed while ThyssenKrupp and ArcelorMittal have both been cancelling or postponing their own green steel projects, citing economic headwinds. The difference is sequencing.
Stegra locked in binding, long-term buyers before chasing financing, not after. That discipline is what turned €6.5 billion from aspirational into genuinely bankable.
The bigger picture
Stegra now sits at the front of a real green steel competitive set, and the EU's Carbon Border Adjustment Mechanism is quietly creating a protected market for premium-priced green steel against cheaper global competitors.
Policy is picking winners here, and right now, Stegra is positioned to be one of them.
The deal
Allianz — German battery storage stake
The world's largest insurer just made its first-ever bet on batteries.
789MW
Capacity
€500M
Investment
Who's involved
Allianz Global Investors
Buyer (50% stake)
Asset manager for the world's largest insurance group, managing €591 billion. This is AllianzGI's first-ever direct equity investment in a battery storage portfolio.
TotalEnergies
Seller & operator
French energy major, selling half the stake while retaining the other 50% and continuing to operate the assets.
Key terms
- 11 projects, 789MW / 1,628MWh, all expected operational by 2028. 70% of the €500M is debt-financed.
- Genuinely vertically integrated: developed by Kyon Energy and equipped with batteries from Saft, both TotalEnergies subsidiaries.
- TotalEnergies keeps operating the sites post-sale, a common structure that lets a seller cash out capital while keeping the operating fee income.
Our take
Insurance money is famously patient and famously cautious, so where it puts its first bet in a new asset class is worth watching closely. Allianz didn't pick a single flagship battery project, it picked a diversified 11-project portfolio, developed and operated by the same corporate group.
That's a low-drama, de-risked way to enter a technology insurers haven't historically touched, and it says something about how mainstream battery storage has become as an investable asset class.
The bigger picture
This is one deal within a much bigger 2026 pattern: German renewables M&A hit its busiest quarter yet, with battery storage involved in over a third of all tracked transactions. Insurers, pension funds, and infrastructure managers are all reaching for the same asset class simultaneously.
Battery storage has quietly moved from a niche technology bet to a mainstream institutional allocation, in the space of a couple of years.
The deal
Engie — a century-old coal plant becomes a battery
Same site, same grid connection, completely different job.
660MWh
Storage
$270M
Investment
Who's involved
Engie Chile
Developer & investor
Subsidiary of French utility Engie, the country's fourth-largest generator. Chose to convert its coal assets in place rather than sell them, unlike several competitors.
Chile's National Electric System
Grid beneficiary
The battery connects directly to the national transmission grid, providing stability services alongside a converted synchronous condenser on the same site.
Key terms
- 240 lithium-ion containers and 30 power conversion systems, connected via a 130 MVA transformer straight into the transmission network.
- Expected to supply 211 GWh annually, enough to power roughly 89,900 Chilean households.
- Honest cost note: early 2024 estimates put this project at around $180M. The final confirmed cost came in at $270M, a real, worth-noting overrun.
Our take
The real advantage here isn't the battery technology, it's the site. Engie kept the existing grid connection and transmission infrastructure instead of building fresh, which almost certainly shaved real time and cost off a project that still ended up 50% over its early estimate.
Engie also chose not to sell off its retired coal assets, the way several competitors have. Converting in place keeps the value of decades of grid infrastructure working, instead of writing it off entirely.
The bigger picture
Northern Chile has seen solar and wind curtailment rise sharply as renewable capacity has outpaced the grid's ability to absorb it. A battery that can soak up that surplus power and release it later is a direct fix for that specific, growing problem.
Engie's own Chile portfolio tells the wider story: renewables and storage made up just 25% of its capacity in 2019. By mid-2026, that's 50%, on track for 71% by 2027. This one project is a small piece of a much bigger, already-underway transition.